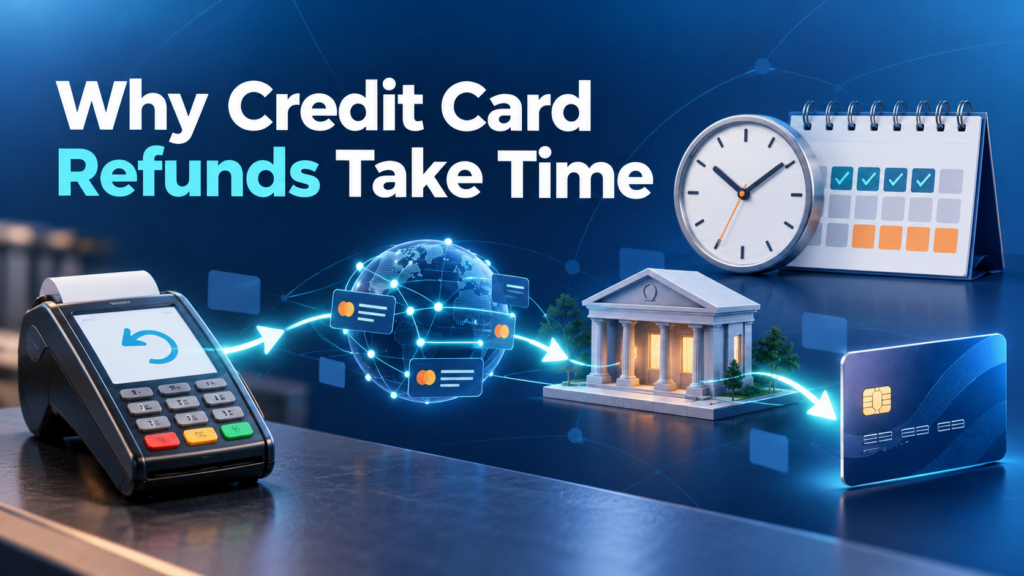
Why Credit Card Refunds Take Time to Reach a Customer
A merchant can issue a refund in seconds, yet the customer may not see the money for several business days. That delay often leads to worried calls and accusations that the business never processed the credit. Understanding the refund timeline helps merchants set realistic expectations and reduce unnecessary disputes. Refunds move through several systems. The…

Delayed Capture in Credit Card Processing: When Should Merchants Use It?
Most card sales are authorized and captured as part of one smooth checkout process. In some businesses, however, the final amount or fulfillment status is not known immediately. Delayed capture allows a merchant to authorize the card first and complete the charge later, within the time and rules allowed by the processor and card network….
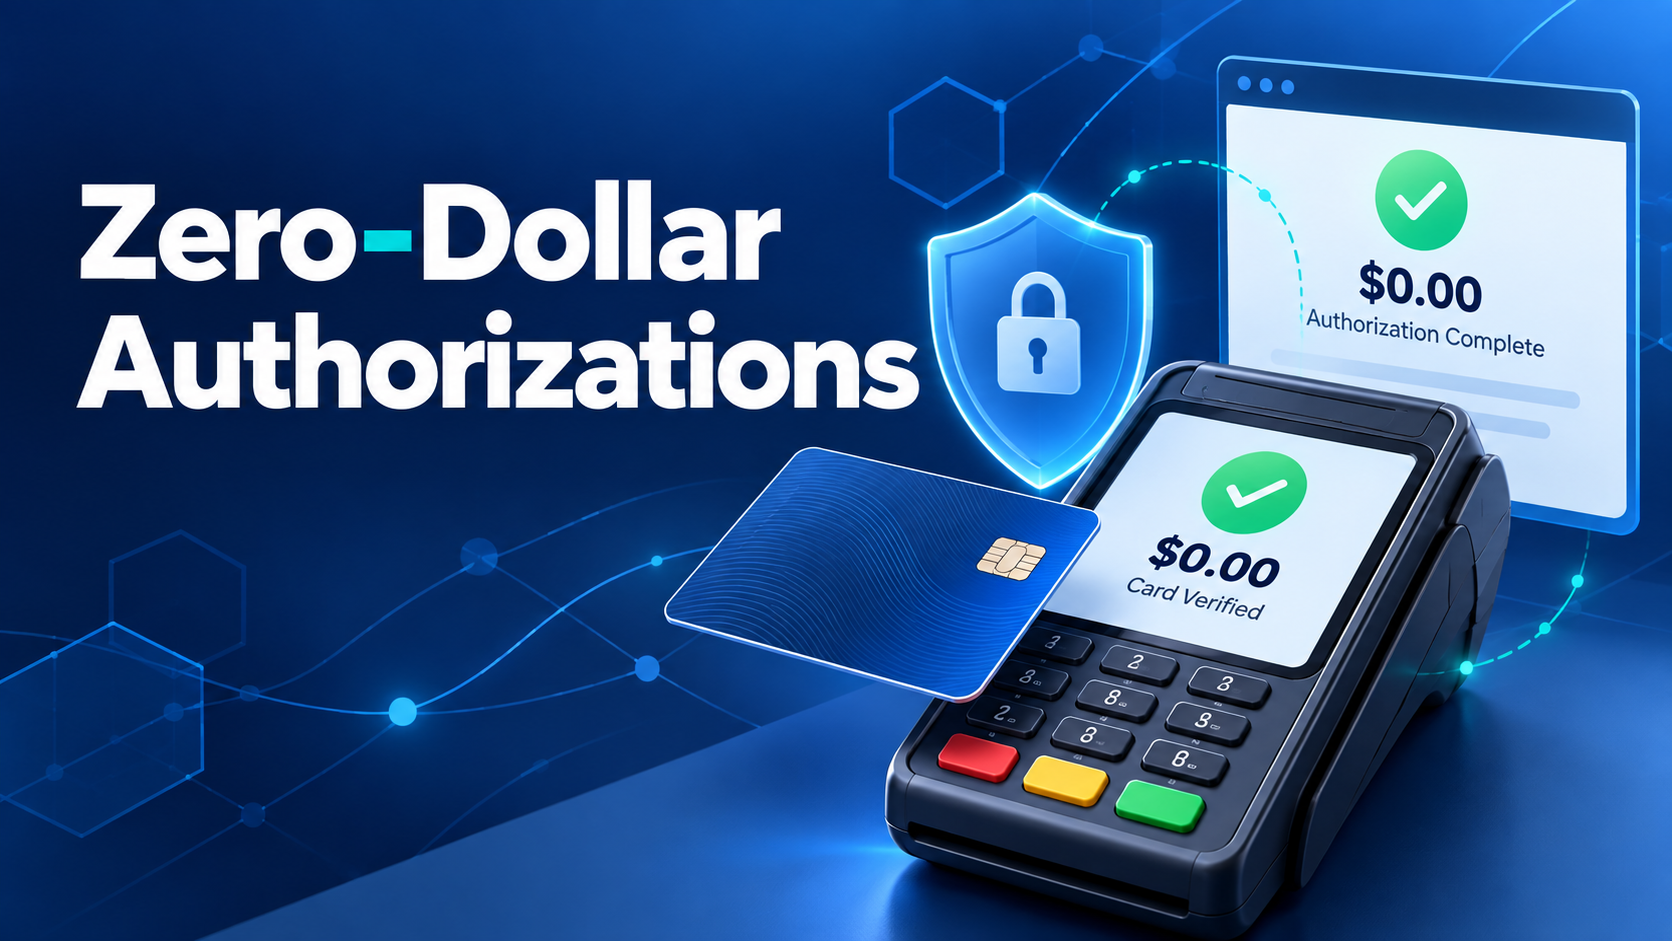
Zero-Dollar Authorizations: How Card Verification Works Without a Charge
Sometimes a business needs to confirm that a card is valid without actually charging the customer. A zero-dollar authorization can perform that check by sending card information to the issuer with an amount of $0.00. The response may confirm that the account exists and that basic verification data matches, but it does not guarantee payment…
Card-on-File Payments: How Merchants Can Store Credentials More Safely
Keeping a customer’s card on file can make future payments faster and easier. It is useful for memberships, recurring services, medical balances, professional fees, rentals, and businesses that bill after work is completed. The convenience is real, but merchants need a secure process for consent, storage, and future use. A business should never keep full…
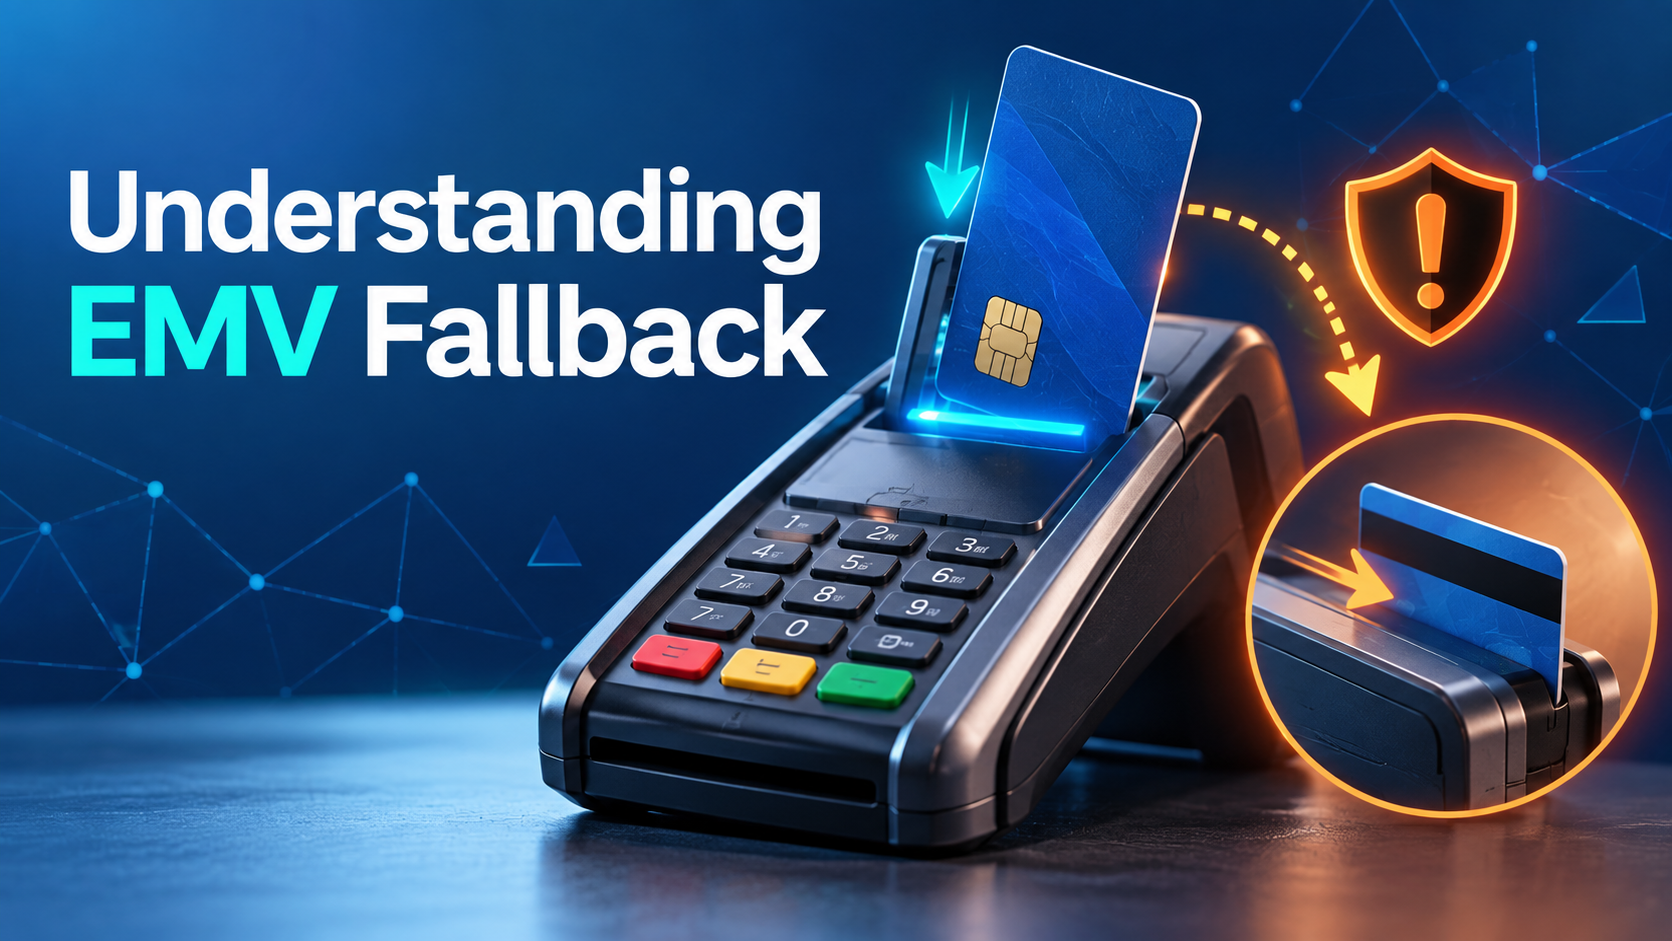
What Is an EMV Fallback Transaction and Why Does It Matter?
When a chip card is inserted into an EMV terminal, the chip should communicate with the device and create a secure transaction. If that process fails and the terminal allows the magnetic stripe to be swiped instead, the payment may be recorded as an EMV fallback transaction. Fallback can be legitimate, but repeated use creates…
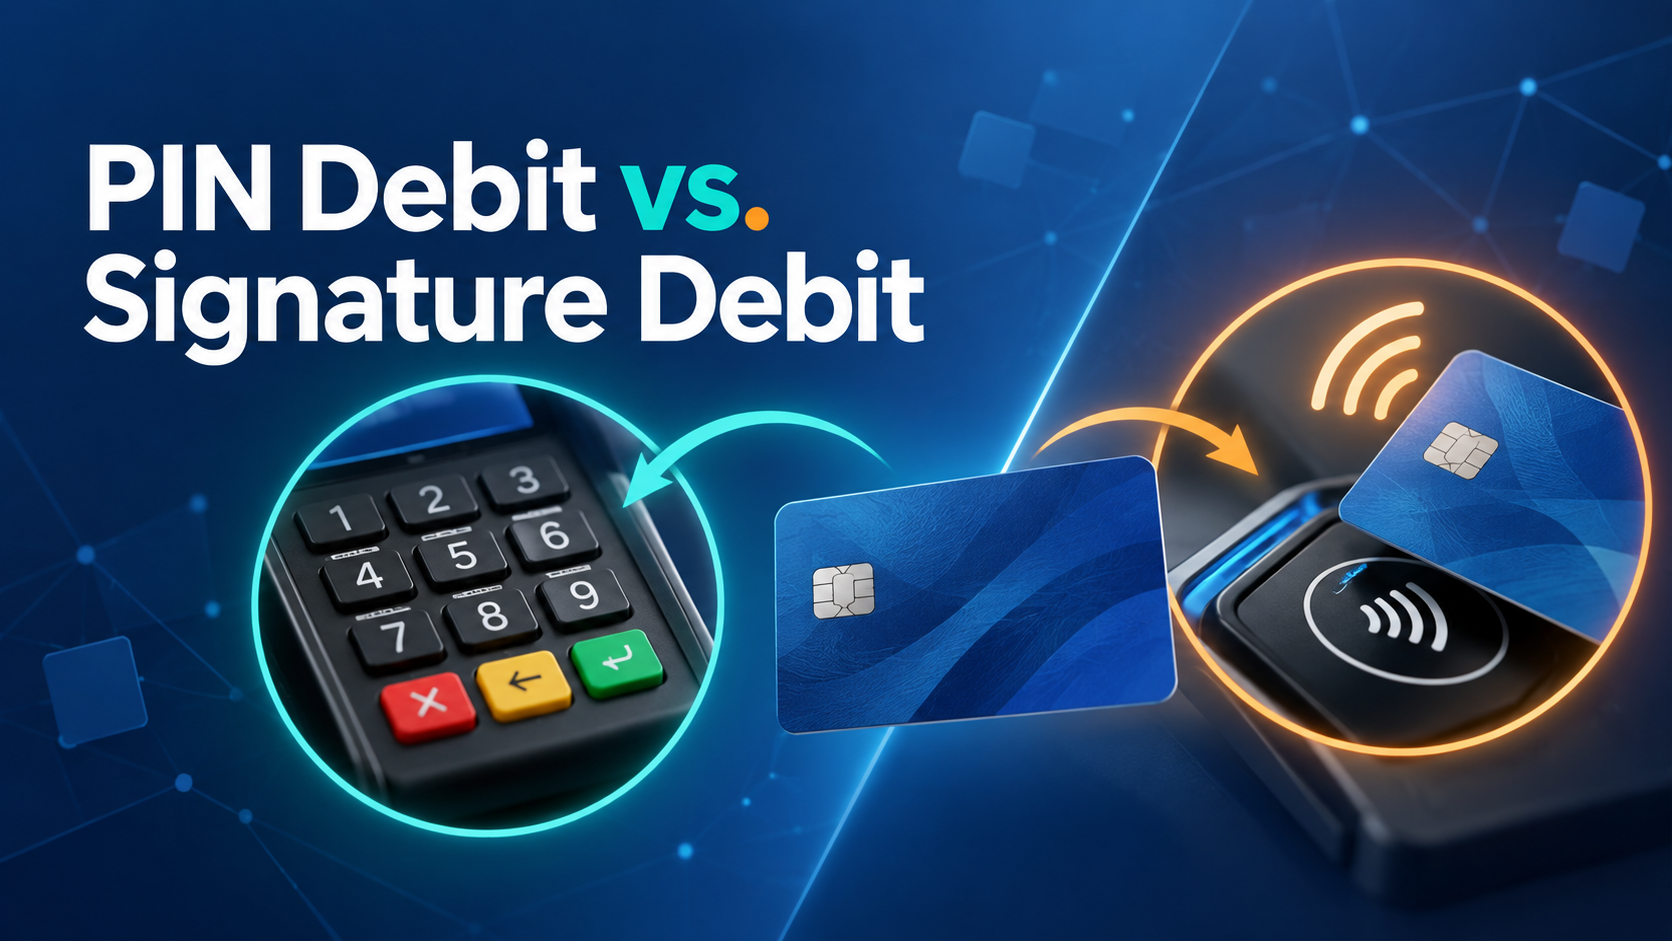
PIN Debit vs. Signature Debit: What Is the Difference for Merchants?
A customer may use the same debit card in two different ways at checkout: entering a PIN or completing the transaction without one. Both options draw money from a checking account, but they can travel across different payment networks and may carry different costs, security features, and dispute rules for the merchant. PIN debit usually…
Partial Approvals and Split Tender Payments: What Merchants Should Know
A card does not always decline simply because the account lacks enough money for the full purchase. In some situations, the issuer may approve part of the amount instead. This is called a partial authorization, and it allows the customer to pay the remaining balance with another payment method. Partial approvals are especially common with…
Why Duplicate Credit Card Charges Happen and How Merchants Can Prevent Them
Few payment problems frustrate customers faster than seeing the same purchase twice. Duplicate credit card charges can lead to refund requests, disputes, negative reviews, and extra work for employees. Fortunately, many duplicates come from preventable checkout habits or system settings rather than intentional misconduct. One common cause is retrying a transaction too quickly. A terminal…
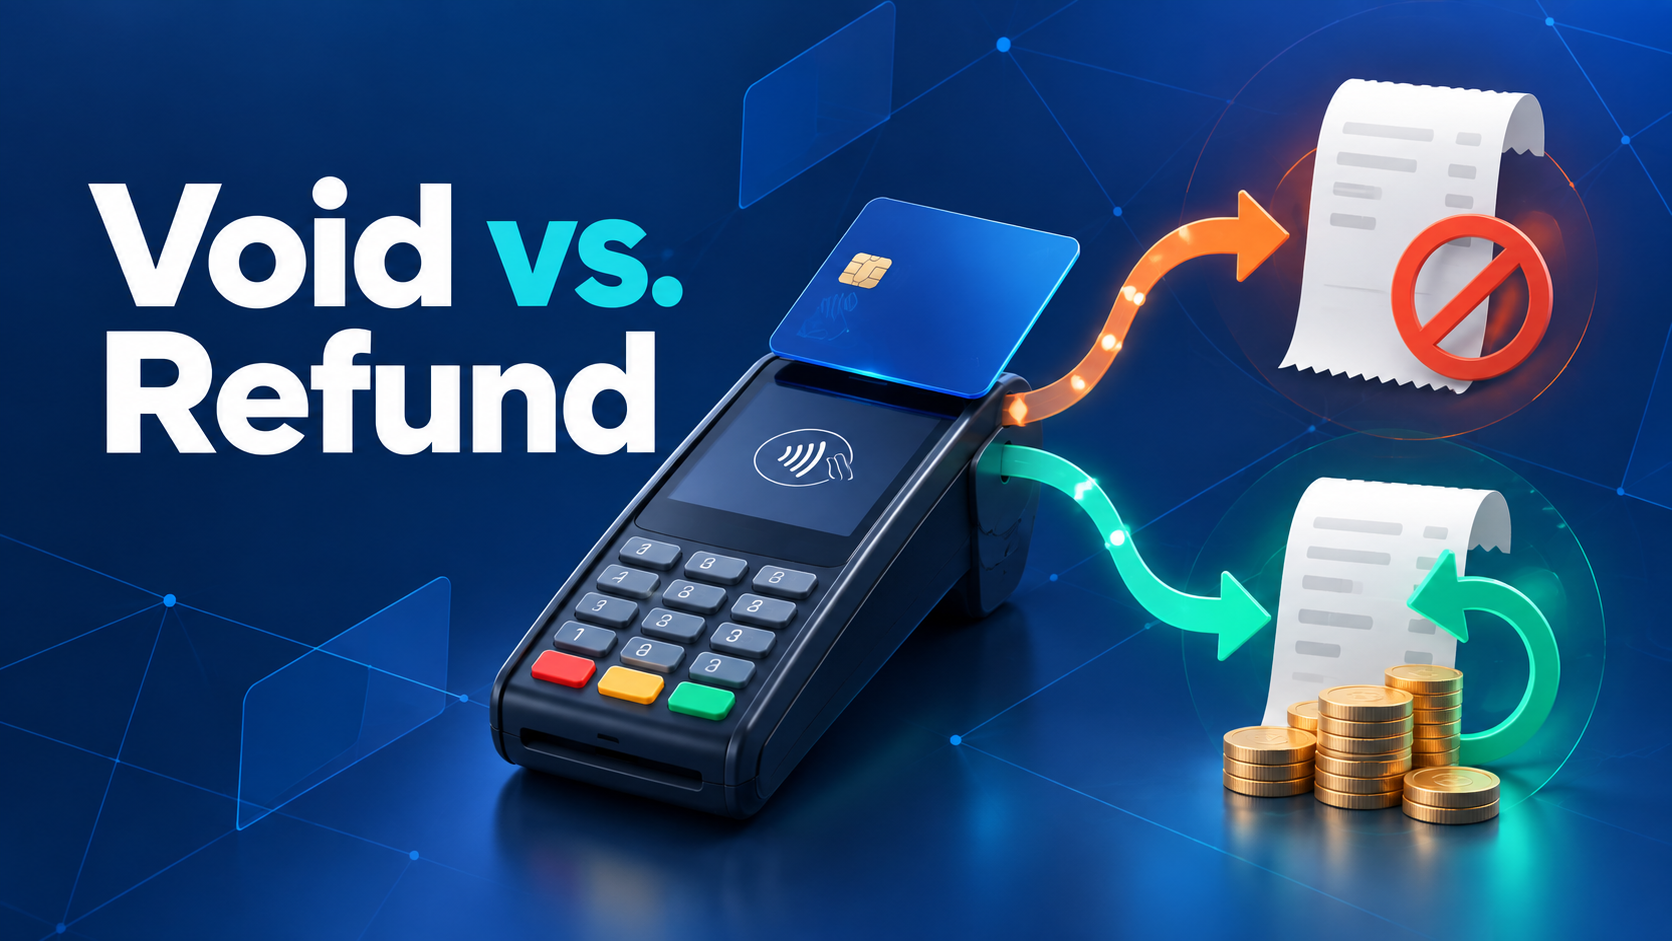
Void vs. Refund: What Is the Difference in Credit Card Processing?
A void and a refund both return money to a customer, but they happen at different points in the payment process. Understanding the difference can help a business avoid unnecessary fees, keep reports accurate, and give customers clearer expectations when a transaction needs to be reversed. A void cancels a transaction before it settles. If…
How Payment Processing Can Help Businesses Improve Accounts Receivable
Slow accounts receivable is often treated as a customer problem, but the payment process may be adding friction. If clients must find a paper invoice, write a check, and mail it, even willing customers can delay. Modern payment tools give them a faster path while giving the business better visibility into what remains unpaid. Why…
What Happens to Credit Card Payments When a Customer Gets a New Card?
A customer replaces an expired, lost, or compromised card, yet a familiar subscription may continue billing without interruption. That can be confusing until you understand account updater services and network tokens. In some payment setups, the stored payment credential can be refreshed without the merchant seeing or handling the new card number. Why it matters…
Why Large or Unusual Transactions Can Trigger a Merchant Account Review
A legitimate sale can still look unusual to a payment processor. Accounts are approved and monitored using expected monthly volume, average ticket size, sales channels, products, delivery times, refunds, and processing history. When activity changes sharply, automated controls or risk teams may pause to ask whether the account is still operating as described. Why it…