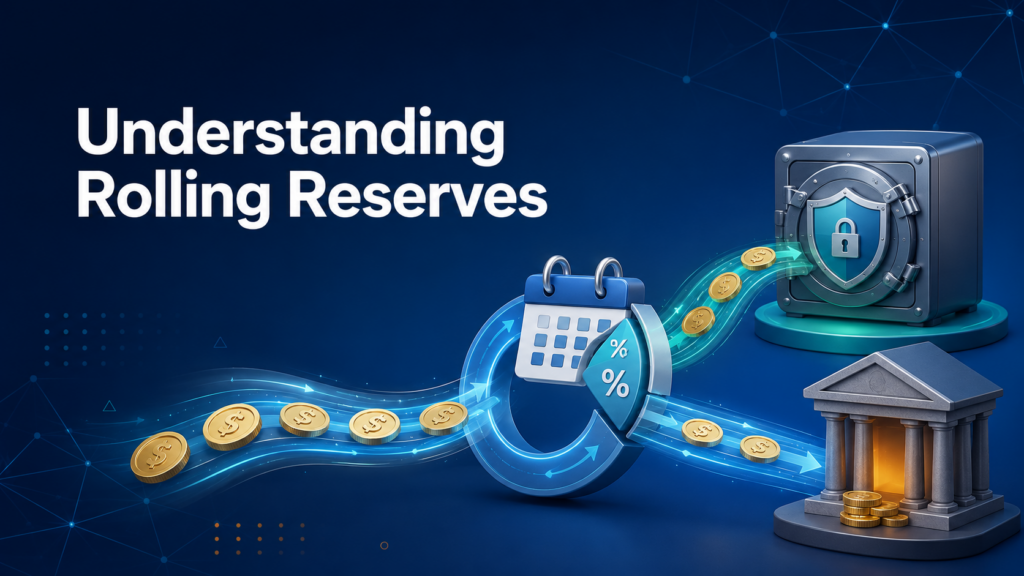
A rolling reserve can surprise a merchant who expects every approved dollar to reach the bank. Under this arrangement, the processor temporarily holds a percentage of each day’s card sales in a reserve account. The money still belongs to the merchant, but it is released later according to the account agreement, often on a rolling schedule.
Why it matters
Reserves are designed to cover financial exposure from chargebacks, refunds, fraud, or a business closing before delivering what customers purchased. They are more common when products ship far in the future, sales are highly seasonal, tickets are large, or an industry has a history of elevated disputes. A new business without processing history may also face additional caution.
Where problems begin
Suppose a processor holds ten percent for 180 days. Ten percent of today’s settled sales enters the reserve, and, assuming no adjustments, that amount becomes eligible for release about six months later. New sales continue to create new reserve entries, which is why it is called rolling. The exact percentage, term, release conditions, and permitted deductions should be stated in writing.
What merchants can do
A reserve affects working capital, so merchants should include it in cash-flow planning rather than treating held funds as immediately available. Reconcile reserve additions and releases every month. Ask how chargebacks or refunds are deducted and what happens if the account closes.
A practical next step
Reserve terms may be reviewed as the business builds a stable record. Low dispute rates, accurate delivery promises, solid financials, consistent volume, and prompt responses to information requests can support a request for reduction. There is no guaranteed timeline, but organized documentation makes a stronger case. Before signing, compare the reserve’s real cash-flow impact alongside rates and fees; the lowest advertised price may not be the best offer if too much revenue remains unavailable.
When comparing offers, model the reserve with real numbers. A five-percent hold on $100,000 in monthly sales means $5,000 of new cash is unavailable each month until releases begin. That can affect payroll, inventory, and advertising. The percentage alone does not show the full effect; timing is equally important.
Review it regularly. Train staff before problems appear.