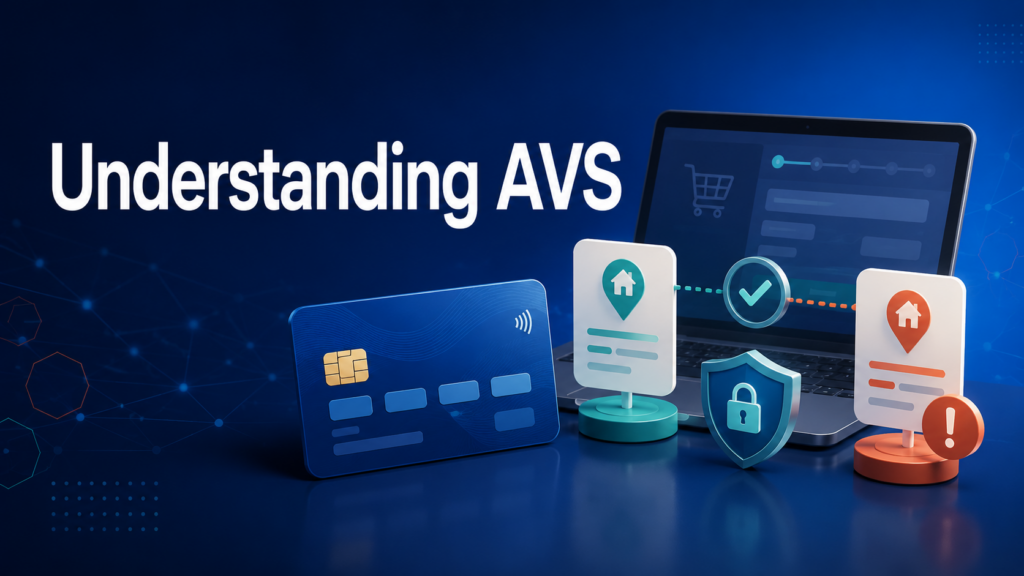
Address Verification Service, usually shortened to AVS, compares numeric parts of a customer’s billing address with information held by the card issuer. It is commonly used for ecommerce, phone, and other card-not-present payments where a merchant cannot inspect the physical card.
Why it matters
An AVS response may indicate that the street number and postal code match, only one matches, neither matches, or the issuer could not perform the check. It does not confirm that the buyer is honest, and a mismatch does not automatically prove fraud. Customers move, mistype information, use corporate cards, or enter a shipping address instead of the billing address.
Where problems begin
Merchants should combine AVS with other signals. The card-security code, device behavior, order history, transaction velocity, email quality, shipping destination, and product risk can provide context. A low-dollar repeat customer with a postal-code typo deserves different treatment from a new buyer placing several rushed orders to unrelated addresses.
What merchants can do
Set rules according to the business’s actual risk tolerance. Automatically declining every partial match may turn away good customers, while approving every mismatch removes much of the tool’s value. Some orders should be held for manual review or verified through a documented customer contact process.
A practical next step
Record the AVS result with the transaction and learn what each response code means in your gateway. Never ask a customer to send sensitive card details by email to resolve a mismatch. AVS is most effective as one useful clue inside a broader fraud strategy. It can reduce risk and strengthen transaction records, but it should support judgment rather than replace it.
International orders need additional care because address formats and issuer support differ. An unavailable result is not the same as a failed match. Review those transactions with other evidence and the value of the order in mind. Document exceptions so employees apply the same reasoning instead of making a new rule for every customer.
Stay prepared. Review it regularly. Keep the process documented. Clear records make follow-up much easier. Ask questions before changing important account settings. Check the agreement because provider rules and timelines vary. Small operational improvements can prevent expensive payment problems later.